Health Insurance for Each Spanish Visa Type: A Side-by-Side Guide
One of the biggest roadblocks to a successful Spanish residency application is submitting a health insurance policy that looks perfect to you but fails the strict criteria of the Spanish Consulate. I remember the sheer anxiety of my first appointment in London, clutching a folder of documents and wondering if my "gold-tier" international plan would be rejected because it had a tiny deductible I hadn't noticed. This guide breaks down exactly what the Spanish authorities demand for every major visa type to ensure your transition to Mediterranean life is as smooth as possible.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
The Universal Standards for Spanish Residency Insurance
When you apply for almost any residency permit in Spain, the government wants to be absolutely certain that you will not become a financial burden on their public healthcare system. This means your private policy must offer a level of coverage that is "equivalent to the Spanish National Health System." In administrative terms, this boils down to three very specific Spanish phrases that you must see in your policy conditions: sin copagos, sin carencias, and repatriación.
The Non-Negotiable Sin Copago Clause
A copago is a co-payment—a small fee you pay every time you visit a doctor or specialist. While these are common in many countries to keep monthly premiums low, they are a flat-out dealbreaker for Spanish visa applications. The consulate requires a policy with "full coverage," meaning you pay your premium and nothing else when you access care. If your policy summary mentions even a five-euro charge for a GP visit, your visa will likely be denied.
This requirement exists because the Spanish government wants to ensure that foreigners have zero barriers to medical care. They don't want residents avoiding the doctor because of a 20-euro fee, only for a condition to worsen and require emergency public intervention later. When shopping for Private Health Insurance for Spain Visas: What Policies Must Include, always verify that the "zero co-payment" status is clearly stated in English and Spanish.
Why Carencias Can Kill Your Application
Carencias are waiting periods. In many international insurance contracts, you might have to wait three months for a diagnostic test or six months for a minor surgery after the policy starts. For a Spanish visa, the authorities generally demand a policy sin carencias, or at least one where the waiting periods do not apply to essential services. If your policy says you cannot see a specialist for the first 90 days, the consulate may view this as a gap in your "equivalent coverage."
I’ve seen many expats get caught out by this when they try to use their existing international plans. Even high-end global insurers often have standard waiting periods for things like dental or complex imaging. To satisfy the Spanish bureaucracy, you often need a certificate from the insurer explicitly stating that you have full access to all covered services from day one. This is a key factor when Choosing a Private Health Insurer in Spain: What to Compare.
Repatriation and the Final Journey Coverage
The third pillar is the repatriation of remains. It sounds morbid, but it is a legal requirement for most long-stay visas. The Spanish government requires that, in the event of your death, the insurance company will cover the entire cost of transporting your body back to your home country. This is not standard in many basic health plans, so you must ensure it is added as a rider.
Consulates are very specific about this. They don't just want "medical evacuation" (which flies you to a better hospital); they specifically want "repatriation of remains." Providers like Cigna Global often include this in their international modules, but you must check the fine print to ensure the coverage limit is sufficient for the consulate's standards.
Specific Insurance Needs for the Non-Lucrative Visa
The Non-Lucrative Visa (NLV) is perhaps the most scrutinized category when it comes to health insurance. Since this visa is specifically for people who are not working in Spain, the government is extra cautious about your potential medical costs. Unlike the Digital Nomad Visa or a work permit, NLV holders have no immediate path into the Spanish Social Security system, making their private policy their only safety net.
The One-Year Upfront Payment Expectation
One of the quirks of the NLV application is that most consulates—especially those in the United States and the UK—require you to prove that you have paid for your entire first year of insurance upfront. A monthly payment schedule is often rejected because the consulate fears you might stop paying once you arrive in Spain. Providing a receipt for the full annual premium is the only way to satisfy this requirement.
This can be a significant financial hit, often costing between 800 and 1,500 euros depending on your age and health status. However, it is an essential part of the "financial means" demonstration. If you are looking into How Much Private Health Insurance Cost in Spain?, remember to factor in this lump-sum payment for your initial budget.
Full Coverage vs Supplemental Plans
For the NLV, your insurance must be a "comprehensive" policy. This means it must cover everything from primary care and specialists to hospitalization and surgery. You cannot use a "top-up" or supplemental plan that only covers major emergencies. The policy must essentially act as your primary healthcare provider.
Many NLV applicants find success with Innoinsure, as they specialize in policies tailored specifically for the requirements of Spanish consulates. Their certificates are pre-worded to include the necessary "no co-payment" and "no waiting period" language that administrative officers look for. Having a certificate in Spanish is not just helpful; it is often mandatory to avoid expensive sworn translations later.
Digital Nomad Visa Insurance Nuances
The Digital Nomad Visa (DNV) has changed the landscape of residency in Spain, and with it, the insurance requirements have become slightly more complex. Depending on whether you are an employee of a foreign company or a self-employed freelancer, your path to healthcare coverage—and what you need for the visa—can vary wildly.
Freelance Nomad Requirements
If you are a self-employed nomad (freelancer), the Spanish government initially requires you to have private health insurance that meets the same strict "full coverage" criteria as the NLV. However, once you arrive in Spain and register as an autónomo (freelancer), you will begin paying into the Spanish Social Security system. This eventually grants you access to public healthcare.
The "catch-22" is that you need the private insurance to get the visa in the first place. Most nomads choose a policy from a provider like SafetyWing for the initial transition if they are on a shorter-term nomad stay, but for the actual residency application, you need a policy that the Spanish Extranjería (Immigration Office) recognizes. Be prepared to maintain your private policy for at least the first few months until your Social Security registration is fully processed and you can obtain your health card.
Employees vs Social Security Integration
If you are an employee of a foreign company and your company has a social security agreement with Spain (common within the EU and with some bilateral partners like the UK or USA), you might be able to use a document called an S1 or a certificate of coverage. This proves you are still paying into your home country's system and that Spain should provide you with public care based on those contributions.
However, the bureaucracy of processing an S1 can take months. Many DNV applicants find it much safer to purchase a one-year private policy to ensure their visa is approved without delay. Once you are settled and your public access is confirmed, you can decide whether to keep the private cover for faster specialist access or rely solely on the public system. Understanding Who Can Access Public Healthcare in Spain? Eligibility Basics is crucial for nomads deciding on their long-term health strategy.
Student Visa Health Insurance Compliance
Students often face a different set of challenges. While the insurance must still be comprehensive, the budget for a student is usually tighter. Furthermore, the length of your stay (under 180 days vs. over a year) dictates exactly what kind of policy you need to show at the consulate.
Minimum Coverage for Short-Term vs Long-Term Studies
If your study program is less than six months, the requirements are sometimes more relaxed, and a high-quality travel insurance policy might suffice. However, for a "long-term" student visa (over 180 days), you must have a policy that mirrors the residency requirements: no co-payments, no waiting periods, and full hospitalization.
Many students attempt to use the insurance provided by their home university. While these plans are often excellent, they frequently lack the specific "repatriation of remains" clause or have a "deductible" (the American version of a co-payment). If your university insurance has a 100-dollar deductible, it will likely be rejected. You are often better off buying a local Spanish policy designed for students, which is usually quite affordable for those under age 30.
Handling Pre-existing Conditions as a Student
One of the hurdles students often face is the "pre-existing condition" exclusion. Spanish private insurers are businesses, and they may exclude coverage for chronic conditions you had before arriving. For visa purposes, the consulate generally wants to see that your insurance covers you for "all risks."
If you have a chronic condition, you might need to look at international providers like Cigna Global, who can sometimes underwrite pre-existing conditions (though often at a higher premium). If your private policy excludes your primary health concern, you should research How to Get a Spanish Health Card (Tarjeta Sanitaria): Step‑by‑Step to see if your student status allows you to opt into the public system once you arrive, providing you with a secondary safety net.
Comparison of Visa Types and Insurance Requirements
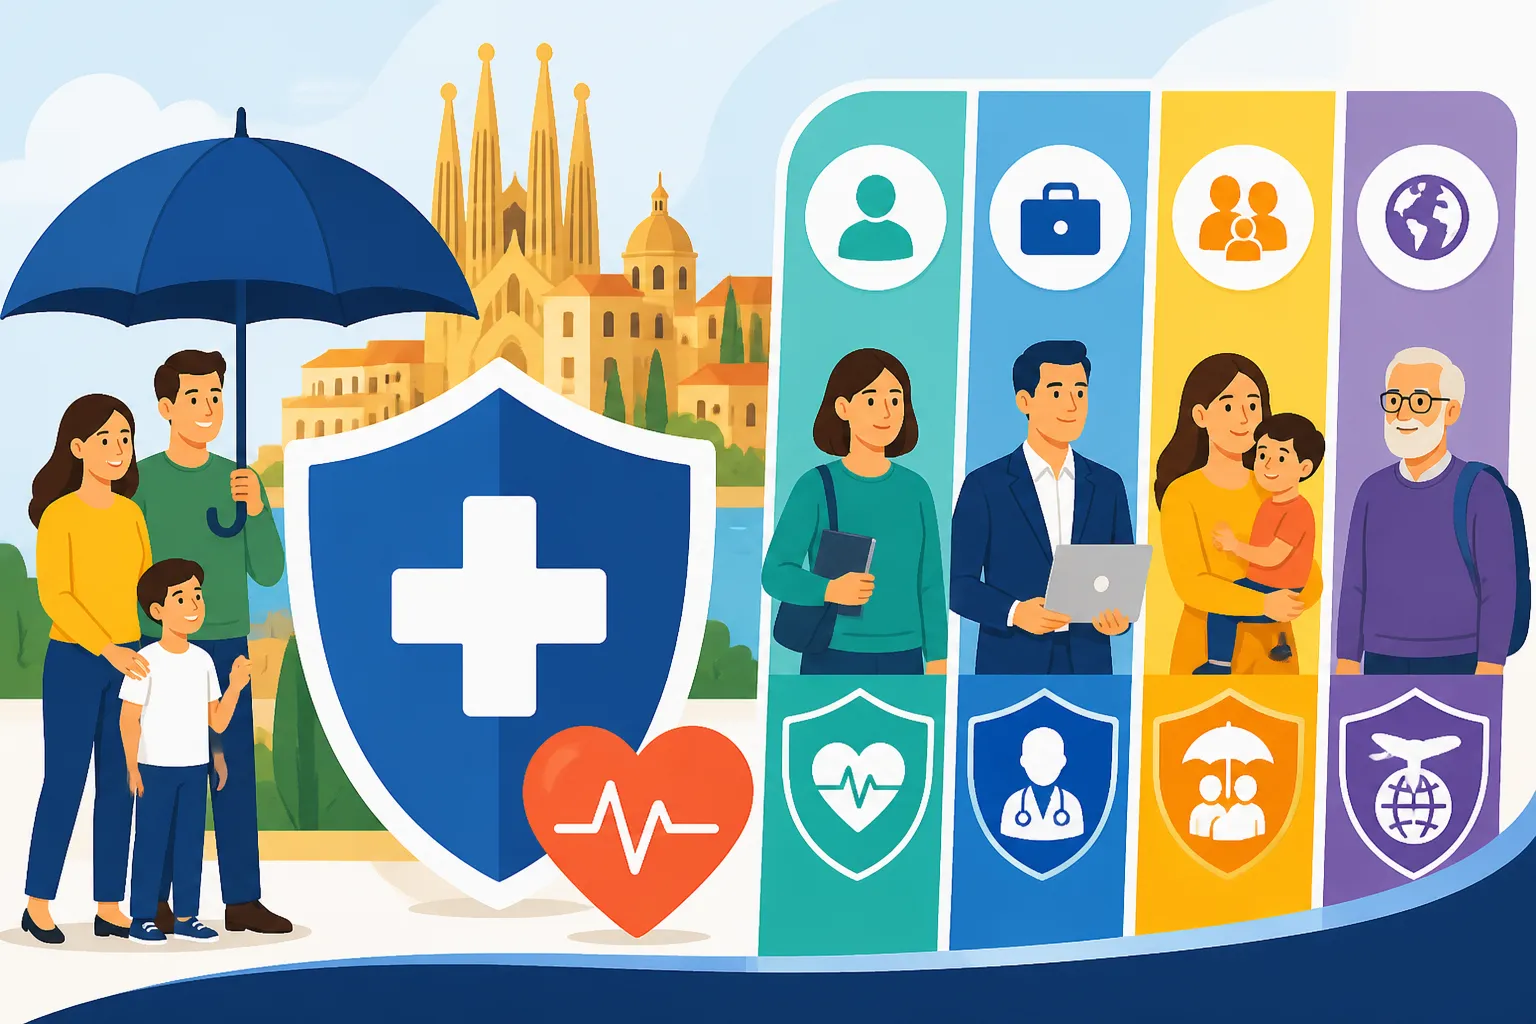
To help you visualize the differences, I’ve put together this side-by-side comparison of the most common visa categories and their typical insurance expectations at the Spanish consulates.
| Visa Type | Mandatory "Sin Copagos" | Upfront Payment Required | Repatriation Clause | Path to Public Healthcare |
|---|---|---|---|---|
| Non-Lucrative (NLV) | Yes, strictly enforced | Yes, full year typically | Mandatory | Only after 1 year (via Convenio Especial) |
| Digital Nomad (DNV) | Yes, for application | Usually monthly is okay | Mandatory | Yes, via Social Security contributions |
| Student Visa | Yes (for >180 days) | No, usually monthly | Mandatory | Limited (usually private only) |
| Golden Visa | Yes | Yes | Mandatory | No (unless working in Spain) |
| Work Permit | No (Employer covers) | N/A | N/A | Yes, from day one of contract |
Golden Visa and Family Residency Permits
The Golden Visa (Residency by Investment) and Family Reunification permits carry their own specific weight. For the Golden Visa, the applicant must show they have insurance for themselves and all dependents included in the application. Because Golden Visa holders are often high-net-worth individuals, the consulates are usually quite strict about the "premium" nature of the policy.
Insurance for the Whole Family Unit
When moving as a family, your insurance policy must list every member clearly. For the Family Reunification visa, the "sponsor" (the person already living in Spain) often needs to prove that their existing insurance can be extended to their family members or that a new, compliant policy has been purchased for them.
It is important to note that if the sponsor is already working and has access to the public system, they can sometimes add their family members as "beneficiaries" of their public cover. However, if the family is applying from abroad, the consulate may still require a private policy for the initial entry. You should check Spain Healthcare System for Expats: Public vs Private to see how these two systems can work together for a family unit.
Coverage for Self-Employed Residents
If you are moving to Spain to start a business or are applying as a "Highly Qualified Professional," your insurance requirements may be tied to your employment contract. However, for the initial "application phase" from your home country, a private policy is almost always the bridge that gets you through the door.
I’ve often advised clients in this category to look for policies that allow for easy cancellation or downgrading once their Social Security payments kick in. Some providers are more flexible than others when it comes to shifting from a "visa-compliant" policy to a "supplemental" policy once you have your public health card in hand.
Provider Breakdown and Comparison
Choosing the right brand depends on your specific visa and your long-term plans. Not all "international" insurance is created equal in the eyes of a Spanish civil servant.
When to Choose Cigna Global for Portability
Cigna Global is a powerhouse for expats who move between countries. If you are a digital nomad who spends six months in Spain and six months in Portugal or Greece, their international portability is a massive advantage. For the Spanish visa, you must ensure you select the "Close to Home" or "International" module that includes Spain and specifically request a "Certificate for Spanish Residency" to ensure the zero co-payment wording is included.
Innoinsure and Local Spanish Expertise
Innoinsure has carved out a niche by working directly with Spanish insurers like DKV or ASISA to provide policies that are "pre-approved" in the minds of consulate officers. Their systems are designed to spit out the exact certificate you need with the specific legal jargon required by Spanish law. If you want the "path of least resistance" for an NLV or Student Visa, a local specialist like this is often the safest bet.
SafetyWing for Flexible Nomad Starts
While SafetyWing is legendary in the nomad community for its flexibility and low cost, it is primarily a travel medical insurance. For a formal residency application (like the DNV or NLV), you need to be very careful. Their standard Nomad Insurance may not meet the "sin carencias" or "sin copagos" requirements of every consulate. However, for the initial move-in period or for nomads who are simply visiting Spain while they decide on residency, it offers excellent emergency peace of mind.
Common Pitfalls and How to Avoid Rejection
The most heartbreaking stories I hear from the expat community are the ones where a visa is rejected after months of waiting because of a simple paperwork error. Bureaucracy in Spain is a ritual, and you must play by the rules.
- The Translation Trap: Even if your policy is from a world-class insurer, if the certificate is only in English, many consulates will reject it. Always ask your insurer for a bilingual certificate or one specifically in Spanish.
- The "Travel Insurance" Label: If your policy document says "Travel Insurance" anywhere on the front page, the consulate might reject it for a long-stay visa. They want to see "Health Insurance" or "Medical Insurance for Residents."
- Missing Payment Proof: Simply showing a policy schedule isn't enough. You must show the bank transfer or the receipt showing the premium has been paid in full.
- Dates of Coverage: Your insurance must start on or before the date you intend to enter Spain. If your visa starts on September 1st but your insurance starts on September 15th, your application is incomplete.
Before your appointment, I highly recommend reviewing What to Bring to Your First Doctor Visit in Spain (Documents Checklist). Even though this is for the doctor, it lists the types of ID and policy numbers you'll need to have organized from day one. Being organized doesn't just help with the visa; it helps you navigate the system once you're actually on the ground in Valencia, Madrid, or Seville.
Practical Steps to Securing Your Policy
- Identify your Visa Type: Use the table above to confirm if you need a full year paid upfront.
- Request a Quote: Get quotes from at least two providers, such as Innoinsure or Cigna Global, and explicitly state: "I need this for a Spanish Residency Visa."
- Review the Certificate: Before paying, ask to see a sample of the "Residency Certificate" they will provide. Check for the words Sin Copagos and Sin Carencias.
- Confirm Repatriation: Ensure the limit for repatriation of remains is at least 30,000 euros (a common minimum requirement).
- Pay and Print: Once you have the policy, print the certificate, the receipt of payment, and the summary of benefits in both Spanish and English.
Navigating the Spanish medical landscape is a learning curve. Once you have your visa and your private policy, you might still find yourself confused by how to actually see a doctor. You'll want to learn How to Book GP Appointments in Spain: Apps, Phones, and Walk‑ins to make sure you're getting the value out of that premium you just paid.
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute legal or professional medical advice. Immigration requirements in Spain are subject to change without notice and can vary significantly between different Spanish Consulates and Autonomous Communities. Always verify the latest requirements with the official Spanish Consulate in your jurisdiction or consult with a qualified immigration lawyer before purchasing an insurance policy for your residency application. All brand mentions are based on common expat usage and do not imply a guarantee of visa approval.