How to Transfer a UK or US Pension to Spain (High-Level Steps)
Moving your hard-earned retirement savings across borders feels like navigating a labyrinth where the walls are made of tax forms and the floor is potentially lava. I remember the paralyzing fear that one wrong box checked on a Spanish form would trigger a massive tax penalty I’d never recover from. This guide solves the mystery of transferring UK or US pensions to Spain.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Understanding the Landscape of International Pension Transfers
When you first land in Spain, the focus is usually on finding the perfect neighborhood or mastering the art of the three-hour lunch. But once the dust settles, the reality of your financial future starts to loom. You have years, perhaps decades, of contributions sitting in a 401k in the States or a SIPP in the UK, and you need to know if that money is safe, accessible, and tax-efficient while you reside under the Spanish sun.
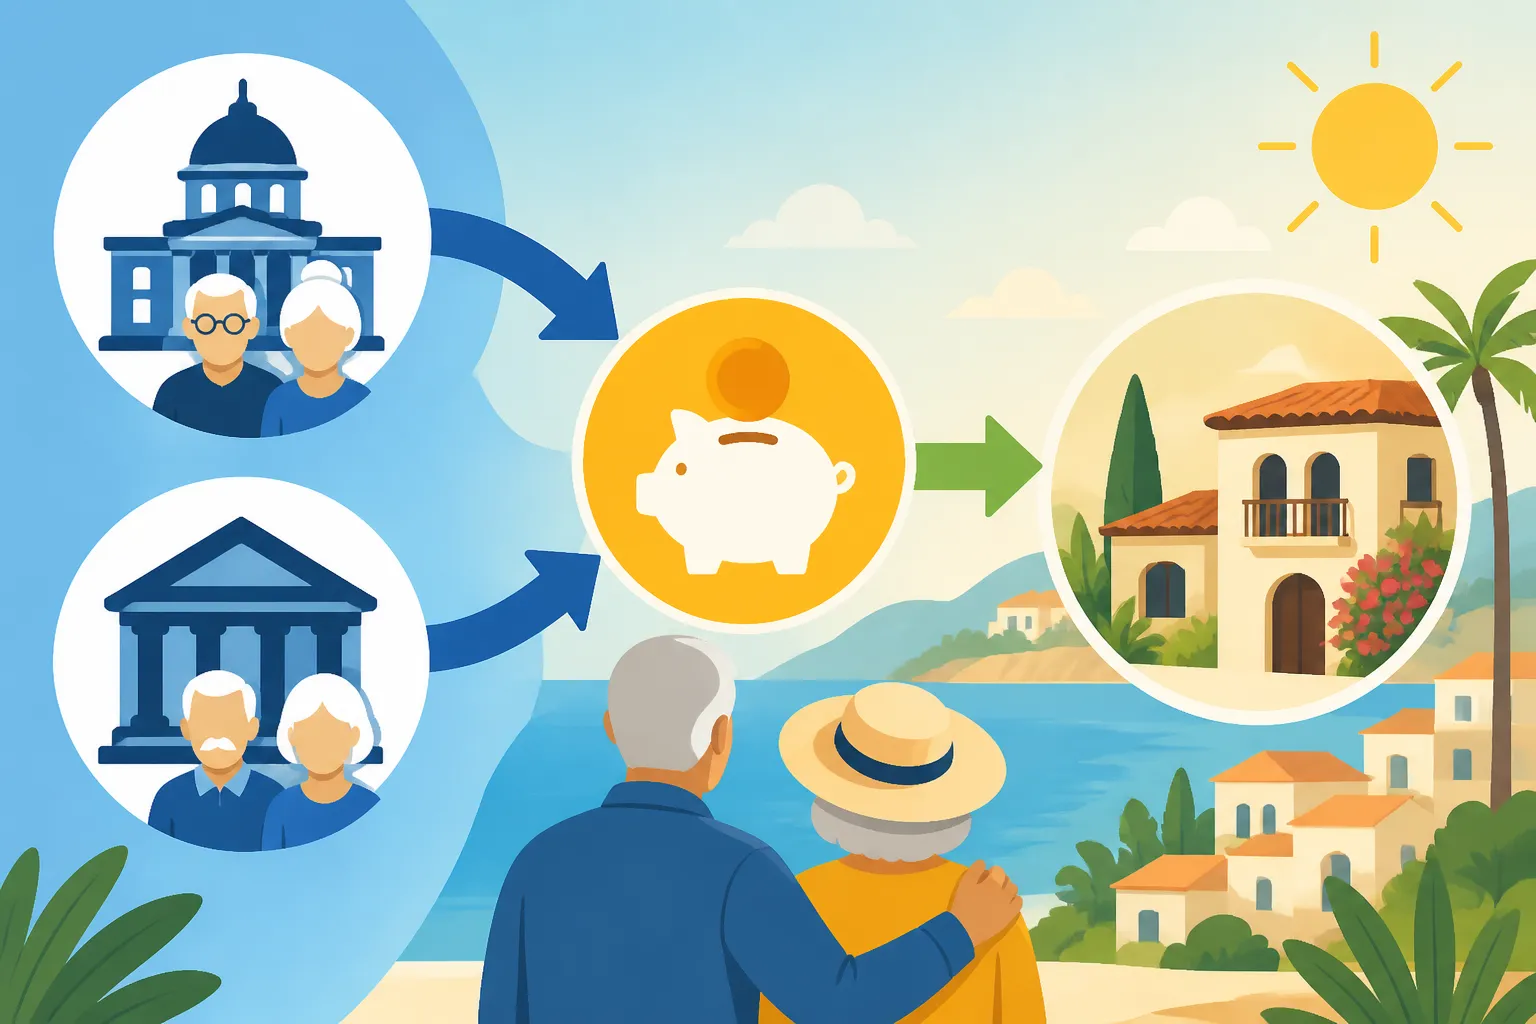
The first thing to realize is that "transferring" a pension doesn't always mean moving the physical pot of money into a Spanish bank account. In many cases, it’s about strategically managing how and where that money is held to minimize the bite taken by the Agencia Tributaria (the Spanish tax office). Spain has a very specific way of looking at foreign income, and they are notoriously thorough. If you are a resident, they want to know about your global assets. This is where Tax Residency in Spain: 183‑Day Rule and Practical Tests becomes the most important document in your arsenal. Once you cross that 183-day threshold, your pension is no longer just a "foreign account"; it is a taxable reality in Spain.
The logistics differ wildly depending on whether your funds are coming from the UK or the US. For UK expats, Brexit changed the game, turning what was once a relatively smooth EU-to-EU transfer into a "third-country" negotiation. For Americans, the complexity lies in the fact that the US is one of the few countries that taxes based on citizenship, not just residency. This means you’ll likely be dealing with a three-way tug-of-war between you, the IRS, and the Spanish Hacienda. To stay ahead of the game, many expats use specialized services like Taxes for Expats to ensure they aren't accidentally committing tax evasion in two different languages.
The UK Perspective: QROPS and SIPP Options
For those with UK pensions, the term you will hear most often is QROPS (Qualifying Recognised Overseas Pension Scheme). This is a pension scheme based outside the UK that meets certain requirements set by HM Revenue and Customs (HMRC). In theory, you can transfer your UK pension into a QROPS in Spain or another jurisdiction to avoid certain UK tax implications and potentially gain more flexibility.
However, since Brexit, the UK has introduced a 25% Overseas Transfer Charge on transfers to QROPS unless specific residency requirements are met. If you are living in Spain and you transfer to a QROPS in another EEA (European Economic Area) country, you might avoid this charge, but the rules are incredibly granular. Many expats find that keeping their money in a UK-based SIPP (Self-Invested Personal Pension) is actually simpler. You can still draw your pension from Spain, but you must be aware that the 25% tax-free lump sum you’d get in the UK is generally not recognized as tax-free by Spain. The Hacienda tends to view it as regular income, which can be a nasty surprise if you haven't budgeted for it in your Cost of Living in Spain: Realistic Budgets and Savings Tips calculations.
The US Perspective: IRAs, 401ks, and the IRS
If you’re coming from the US, "transferring" a pension to a Spanish plan is almost never a good idea. Spanish pension plans (Planes de Pensiones) are structured very differently, and moving a 401k or IRA into one would likely be treated by the IRS as a full distribution. This means you’d be hit with immediate US income tax and, if you’re under 59.5, a 10% early withdrawal penalty.
Instead, US expats typically maintain their US brokerage accounts. The challenge here is that many US providers will close your account if they find out you live abroad because they don't want the compliance headache. You’ll need a "brokerage for expats" or a way to maintain a US nexus. When the money eventually moves from your US account to your Spanish life, you’ll be dealing with the Double Tax Treaties: Avoiding Double Taxation as a Spain Resident. Generally, you pay tax in Spain first, and then claim a credit on your US return, but the paperwork is dense.
The Step-by-Step Logistics of Moving Your Retirement Funds
The process of managing your pension as an expat is less about a single "transfer" event and more about a series of administrative hurdles. You cannot simply walk into a bank in Madrid and ask them to "import" your 401k. It requires a coordinated effort between your home country provider, a cross-border financial advisor, and your Spanish bank.
Before you start moving digits around, you need a place for them to land. Most traditional Spanish banks will charge you "maintenance fees" that feel like a slow leak in your savings. I’ve found that using a modern, expat-friendly option like N26 is much more efficient for daily management. They provide a Spanish IBAN, which is essential for setting up your life, but their interface is in English and they don't hit you with the "foreigner tax" hidden in high commissions.
Step 1: Evaluating Your Current Scheme's Portability
Your first move is to request a "Cash Equivalent Transfer Value" (CETV) if you’re in the UK, or a full summary of your "Vested Balance" if you’re in the US. You need to know exactly what the "exit" cost is. Some defined benefit schemes in the UK are "unfunded" (like the NHS pension) and literally cannot be transferred to a QROPS.
In the US, check if your provider allows for international wire transfers. If they only issue paper checks (which is shockingly common), you are in for a world of pain. Spanish banks are increasingly refusing to accept foreign checks, or they will hold the funds for 40 days and charge a massive fee. This is where having a digital bridge is vital. Using a service like Wise allows you to receive funds in USD or GBP and convert them to Euros at the mid-market rate, saving you thousands compared to the terrible exchange rates traditional banks offer.
Step 2: Formalizing Your Spanish Tax Status
You cannot effectively manage a pension transfer until you have your NIE (Número de Identidad de Extranjero) and, ideally, your TIE (Tarjeta de Identidad de Extranjero). Spanish financial institutions and tax authorities won't talk to you without them. Once you have these, you must register with the Hacienda.
This is the point where you should read up on Spanish Income Tax (IRPF) 101: Who Pays and When. Your pension income will be added to your general taxable base in Spain. If you are drawing a large amount, you could find yourself in a high tax bracket quickly. It is often better to draw smaller, regular amounts rather than large lump sums to keep your tax liability manageable.
Step 3: Notification and Reporting (The Dreaded Modelo 720)
Once your pension is being paid into your Spanish account, or even if it’s just sitting in a foreign account while you live in Spain, you have a reporting obligation. If the value of your foreign assets (including pensions) exceeds €50,000, you must file a Modelo 720.
Failure to file this, or filing it incorrectly, used to carry draconian fines. While the European Court of Justice has forced Spain to scale back those penalties, it is still a high-stakes form. You can find more detail in Modelo 720 and Foreign Asset Reporting: A Practical Overview. This is not something you want to DIY on a Sunday night; get professional help to ensure your pension is declared correctly so it doesn't look like hidden wealth.
Tax Implications and Currency Management
The single biggest mistake I see new expats make is ignoring the "currency ghost." If your pension is in Dollars or Pounds but your rent is in Euros, you are essentially a currency trader whether you like it or not. A 5% swing in the exchange rate can mean the difference between a comfortable retirement and a stressful one.
When moving large sums or even setting up a monthly "salary" from your pension, don't just click "transfer" in your home bank's app. They will skin you on the spread. Using Wise is the industry standard for a reason; you see exactly what you’re getting. If you are transferring a lump sum of £100,000, the difference between a bank rate and a Wise rate can be as much as €3,000. That’s a lot of tapas.
The Spanish Wealth Tax Consideration
Spain is one of the few countries in Europe that still has a Wealth Tax (Patrimonio). This is an annual tax on the net value of your assets, not just your income. Your pension pot, depending on its structure and whether you can access it as a lump sum, might be included in this calculation.
The thresholds vary by region (Comunidad Autónoma), so where you choose to live matters financially. For example, Madrid has historically offered a 100% rebate on Wealth Tax, while other regions are much stricter. You should consult Wealth Tax and Solidarity Tax in Spain: Overview for Foreigners to see if your retirement pot puts you over the limit. If you have a significant pension, you might need to look for Choosing a Gestor or Tax Advisor in Spain: What to Look For to help structure your assets in a way that minimizes this burden.
Managing the US-Spain Tax Treaty
For my American friends, the "Saving Clause" in the US-Spain tax treaty is the thorn in your side. It essentially says the US can tax its citizens as if the treaty didn't exist, but then provides mechanisms to avoid double taxation. Most US Social Security is only taxable in the US, but private pensions and IRAs are usually taxable in Spain.
Because the US tax year and the Spanish tax year align (both are calendar years), the reporting is slightly easier than for the UK (which uses the April-to-April system), but you still need a specialist. Taxes for Expats is particularly good at navigating the "Foreign Tax Credit" vs. "Foreign Earned Income Exclusion" debate, which is vital for pension holders. You want to make sure you’re not paying 20% to Uncle Sam and another 20% to the Hacienda for the same Euro.
Comparison: UK vs. US Pension Handling in Spain
| Feature | UK Pensions (SIPP/Workplace) | US Pensions (401k/IRA) |
|---|---|---|
| Transfer Vehicle | QROPS / International SIPP | Generally remain in US accounts |
| Tax-Free Lump Sum | 25% (UK side), but taxable in Spain | Not applicable (usually fully taxable) |
| Reporting in Spain | Modelo 720 (if >€50k) | Modelo 720 (if >€50k) |
| Currency Risk | High (GBP to EUR) | High (USD to EUR) |
| Double Tax Treaty | Generally taxed in Spain | Complex; US retains some rights |
| Best Strategy | Drawdown into Spanish account | Drawdown via expat-friendly brokerage |
Practical Tips for a Smooth Transition
After years of helping people navigate this, I’ve realized that the "administrative" part of the move is often more exhausting than the physical move. To make your life easier, I recommend keeping a digital folder with every single pension statement from the last three years, translated into Spanish by a sworn translator if you are applying for residency based on these funds.
When you are ready to start receiving payments, make sure your Spanish bank account is fully set up. Using N26 is great for the tech-savvy, as you can manage everything from your phone without needing to make an appointment at a branch three weeks in advance. Just remember that if you are receiving large international transfers, the bank might temporarily "freeze" the funds and ask for proof of origin. This is a standard anti-money laundering check in Spain. Have your pension contract and latest statements ready to email to them immediately.
Finally, don't rush into a QROPS transfer just because a "wealth manager" in a shiny suit told you it would save you taxes. These transfers are often permanent and come with high setup fees. Sometimes, the simplest path—leaving the money where it is and using a smart transfer service to bring it over as needed—is the most cost-effective. Take your time, get a second opinion, and remember that Opening a Bank Account in Spain: Step‑by‑Step for Foreigners is your first real gate to financial freedom here.
Essential Disclaimer
The information provided in this guide is for informational purposes only and does not constitute financial, legal, or tax advice. International pension transfers are highly complex and subject to changing regulations in multiple jurisdictions. You should always consult with a qualified professional who specializes in cross-border financial planning before making any decisions regarding your retirement funds. We are not responsible for any financial losses or tax penalties incurred by following the general steps outlined in this article.